Tesla Model Y Insurance Cost by State
A Model Y costs $1,992 a year to insure in Hawaii and $6,247 in Louisiana. Full state-by-state table with the driver profile and date attached, plus why the same car varies 3×.

Published: Oct 7, 2026
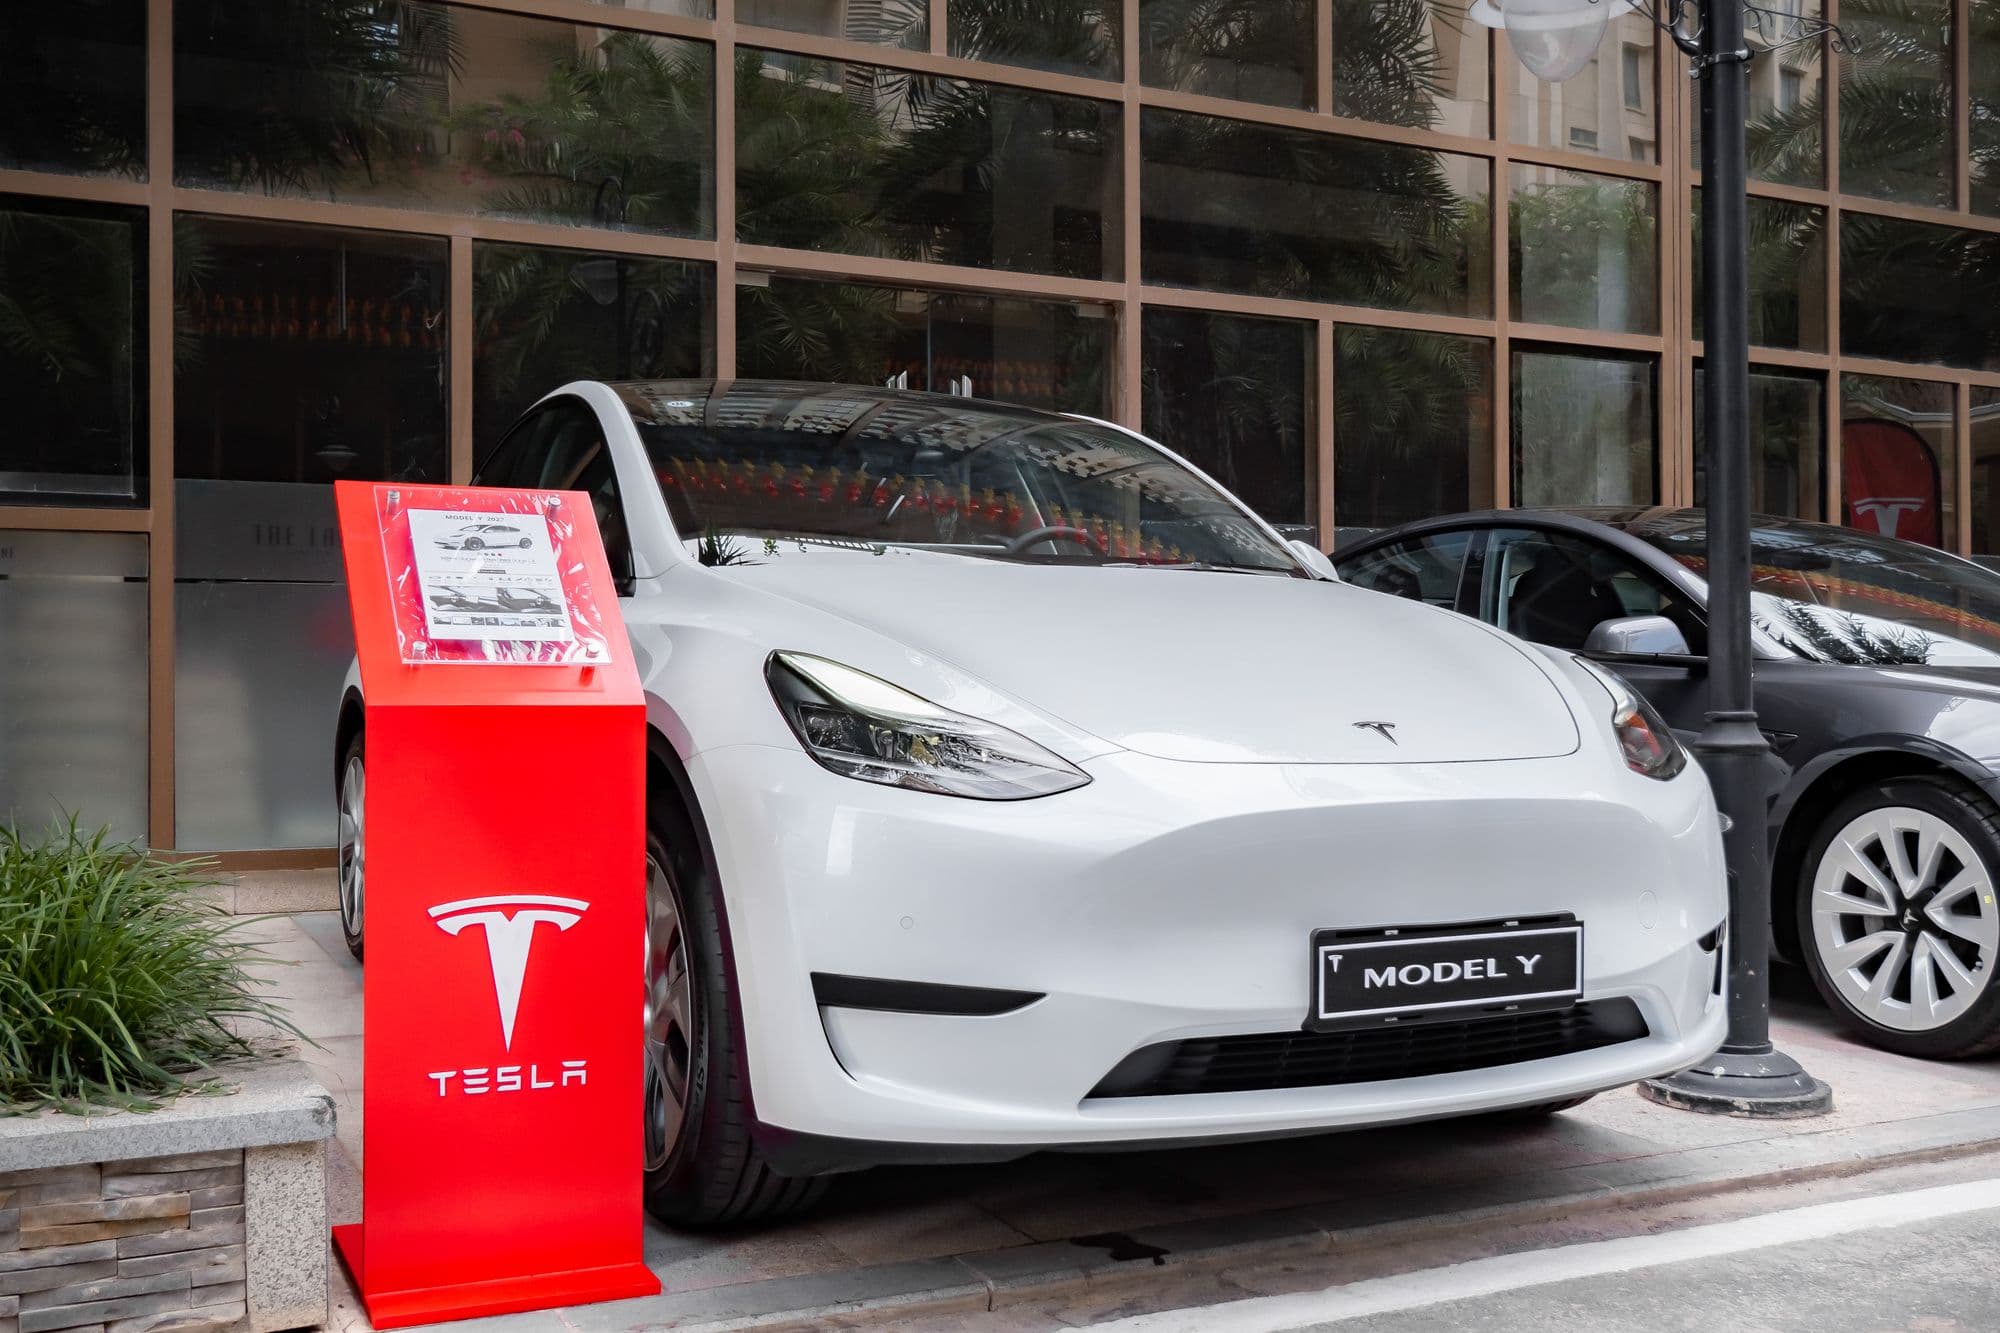
Image source: Pexels
A Tesla Model Y costs $3,836 a year to insure on average, or about $320 a month, for a 40-year-old driver with a clean record and good credit, carrying 100/300/100 limits and a $500 deductible. That is the national average according to Insurance.com. Hawaii is the cheapest at $1,992, while Louisiana is the most expensive at $6,247. However, the cost of insuring a Tesla is far more than a national number: it depends heavily on the state you live in, and below is the breakdown for all 50 states, plus the reasons the gap between them is so wide.
Model Y Insurance Cost in Every State
Where you live can make a bigger difference to your Model Y insurance bill than many drivers expect. The table below shows the average annual full-coverage premiums in every state for a Tesla Model Y insured by the same driver and coverage profile throughout: a 40-year-old with a clean record and good credit, carrying 100/300/100 liability limits, $500 comprehensive and collision deductibles, 10,000 annual miles and a 12-mile commute.
State-by-State Rates
Model Y Insurance Cost in Every State
Average annual full-coverage premiums for a 40-year-old driver with a clean record and good credit, 100/300/100 liability limits, $500 comprehensive and collision deductibles, 10,000 annual miles, and a 12-mile commute.
| State | Annual | Monthly |
|---|---|---|
| Alabama | $3,480 | $290 |
| Alaska | $3,256 | $271 |
| Arizona | $3,736 | $311 |
| Arkansas | $4,227 | $352 |
| California | $4,728 | $394 |
| Colorado | $4,000 | $333 |
| Connecticut | $4,660 | $388 |
| Delaware | $3,907 | $326 |
| District of Columbia | $5,255 | $438 |
| Florida | $4,058 | $338 |
| Georgia | $3,672 | $306 |
| Hawaii | $1,992 | $166 |
| Idaho | $2,395 | $200 |
| Illinois | $3,568 | $297 |
| Indiana | $2,541 | $212 |
| Iowa | $3,418 | $285 |
| Kansas | $3,791 | $316 |
| Kentucky | $4,472 | $373 |
| Louisiana | $6,247 | $521 |
| Maine | $2,373 | $198 |
| Maryland | $4,545 | $379 |
| Massachusetts | $3,098 | $258 |
| Michigan | $5,401 | $450 |
| Minnesota | $3,575 | $298 |
| Mississippi | $4,901 | $408 |
| Missouri | $3,683 | $307 |
| Montana | $3,747 | $312 |
| Nebraska | $3,907 | $326 |
| Nevada | $5,729 | $477 |
| New Hampshire | $2,647 | $221 |
| New Jersey | $4,487 | $374 |
| New Mexico | $3,590 | $299 |
| New York | $4,024 | $335 |
| North Carolina | $2,915 | $243 |
| North Dakota | $3,153 | $263 |
| Ohio | $2,729 | $227 |
| Oklahoma | $3,920 | $327 |
| Oregon | $3,036 | $253 |
| Pennsylvania | $4,140 | $345 |
| Rhode Island | $4,111 | $343 |
| South Carolina | $4,120 | $343 |
| South Dakota | $4,108 | $342 |
| Tennessee | $3,671 | $306 |
| Texas | $4,169 | $347 |
| Utah | $2,882 | $240 |
| Vermont | $2,536 | $211 |
| Virginia | $3,515 | $293 |
| Washington | $2,958 | $247 |
| West Virginia | $3,379 | $282 |
| Wisconsin | $3,985 | $332 |
| Wyoming | $3,072 | $256 |
Source: Insurance.com/Insure.com, April 2026, for the driver profile above. Independently corroborated at the extremes by MoneyGeek's analysis (different profile, $1,000 deductible), which also ranks Louisiana highest and Hawaii lowest.
MoneyGeek's September 2026 analysis uses a different profile and a $1,000 deductible, but it independently puts Louisiana at the expensive end and Hawaii at the cheap end. While the middle of the rankings can move between datasets, the two extremes are remarkably consistent.
The Cheapest and Most Expensive States
The extremes are worth pulling out because they make the state effect much easier to see:
The Extremes
The Cheapest and Most Expensive States
Pulling out the extremes makes the state effect easier to see. The gap between Louisiana and Hawaii is $4,255 a year — more than the entire annual Model Y premium in Hawaii.
| State | Annual premium |
|---|---|
| Louisiana | $6,247 |
| Nevada | $5,729 |
| Michigan | $5,401 |
| Washington, D.C. | $5,255 |
| Mississippi | $4,901 |
| State | Annual premium |
|---|---|
| Hawaii | $1,992 |
| Maine | $2,373 |
| Idaho | $2,395 |
| Vermont | $2,536 |
| Indiana | $2,541 |
The difference between Louisiana and Hawaii is $4,255 a year. That's more than the entire annual Model Y premium in Hawaii. For this particular car, which state you live in matters more than trim, mileage, or model year.
You obviously can't relocate to save on car insurance. But if you're already moving or comparing a new quote after one, this table at least tells you whether the number you're looking at is normal for where you live rather than something worth questioning.
Why the Same Car Costs Three Times More in One State
The Model Y itself isn't changing as it crosses a state line. What changes is the insurance environment around it. Four factors help explain why the same vehicle and broadly similar driver profile can produce dramatically different premiums.
Uninsured Drivers and the Courts
The strongest state-level clue is the number of drivers who don't have enough insurance to cover a crash. The Insurance Research Council reported in February 2025 that 15.4% of U.S. drivers were uninsured in 2023, while 33.4% were either uninsured or underinsured. Mississippi had the highest uninsured rate at 28.2%, while Maine had the lowest at 5.7%.
That lines up strikingly with the Model Y table. Mississippi is the fourth-most expensive state at $4,901, while Maine is the second-cheapest at $2,373. When more drivers around you lack adequate coverage, your own policy may have to absorb more of the financial impact when crashes happen.
The legal system matters, too. Louisiana is an at-fault (tort) state, meaning injury claims generally run through the tort system. That helps explain why it sits at the top of this Model Y table.
Michigan is a different case. Its no-fault system gives drivers choices around personal injury protection, while the default bodily-injury limits are $250,000 per person and $500,000 per accident. Those higher default limits are one reason Michigan can produce unusually high premiums, putting it third on this list at $5,401.
That said, minimum coverage limits alone don't decide the outcome. Maine requires 50/100/25 limits plus uninsured motorist and medical payments coverage — among the highest minimums nationwide — and is still the second-cheapest state on this list.
Total-loss risk adds a fourth wrinkle. Kelley Blue Book reporting has found that insurers are quicker to declare a damaged Tesla a total loss than they might for other vehicles, since even modest collision damage can cost more to repair than the car is worth — a dynamic that pushes baseline premiums up regardless of which state you're in.
Image source: Pexels
Tesla Collision Center Access is Still Limited
As of April 2025, there were just 51 Tesla Collision Centers in the entire United States, spread across only 21 states and territories — and that network has grown since. New York, which had no certified shop as of that April 2025 snapshot, now has at least one in Carle Place. California had 10 shops as of April 2025, and Texas had 9.
Fewer certified shops means longer repair times, more towing and transport, and less competition on labor pricing in states with no local option. Insurers price in the expected cost of getting a car repaired, and geography is a real part of that cost.
The repair bill itself runs higher on EVs generally. Average repairable claim severity for a battery-electric vehicle sits at $6,042 compared to $4,902 for a gas car, and 84.74% of parts spending on EV repairs goes to manufacturer parts rather than cheaper aftermarket alternatives (Mitchell Q2 2026). There's very little relief available on a Tesla repair bill anywhere — and less in a state with no certified shop nearby.
How Your State Regulates Rates
Some states require regular sign-offs on an insurance rate before it can be used. Others let insurers set and use their own rates immediately. That difference changes both how high rates run and how quickly they move.
California is the clearest example, and an unusual one given how large a Tesla market it is. Under Proposition 103, passed in November 1988, the State's Insurance Commissioner must approve a rate before an insurer can use it, and consumers can formally challenge filings through the California Department of Insurance's intervenor program. That prior-approval system is a large part of why California sits mid-table at $4,728 despite having some of the highest repair costs in the country.
It also explains a Tesla-specific quirk: Tesla's Real-Time Insurance isn't available in California, and Tesla's own documentation states that its safety score there is "for educational purposes only" and doesn't affect premiums. Telematics-based pricing of that kind doesn't fit under California's regulatory model.
Why Published Model Y Figures Range From $2,538 to $4,752
If you've searched Model Y insurance elsewhere, you've probably noticed that the numbers don't agree. Published estimates range from $2,538 to $4,752 — an 87% spread.
That doesn't necessarily mean one source is wrong, but rather the underlying profiles can be very different.
$2,538 — NerdWallet, April 2026, Quadrant rate-filing data, base 2025 trim, good drivers
$2,887 — MoneyGeek, September 2026, 40-year-old, 100/300/100, $1,000 deductible
$3,836 — Insurance.com and Insure.com, April 2026, 40-year-old, 100/300/100, $500 deductible
$4,021 — Insurify EV report, 2 June 2026, ages 20-70, $1,000 deductible
$4,601 — CarEdge, with no published date, limits, or deductible
$4,752 — Insurify, September 2026, specifically for the 2025 model year
$3,984 — Compare.com, $332/month, no published date, limits, or deductible
$2,725 to $3,529 — Autoblog, range, no published date, limits, or deductible
The first major difference is the deductible. A $500 comprehensive and collision deductible isn't the same risk to an insurer as a $1,000 deductible, so the resulting premiums won't match. The second is filed rates versus live quotes. NerdWallet's figure uses rate-filing data, while Insurify's methodology is built around quotes served to shoppers. Those approaches are answering different questions.
Model year can also move the number substantially. Insurify's data shows a 2025 Model Y at $396 a month, compared with $237 for a 2021. Insurance.com, meanwhile, gives different annual averages by model year, from $3,343 for 2021 to $3,836 for 2025.
Driver age is the steepest curve of all. The Insurance.com dataset puts an 18-year-old's annual premium at $5,853, compared with $3,836 for a 40-year-old.
For best results, match the source's driver profile, deductible, model year, and date to your own situation before treating its number as a quote. A published figure without those details is difficult to use.
Image source: Pexels
Does Trim Change Your Tesla Model Y Insurance Cost?
Yes, but the difference may be smaller than you expect. Insure.com's matched April 2026 figures put the Model Y Long Range at $3,786 a year and the Model Y Performance at $3,936 for a 40-year-old driver with 100/300/100 limits and a $500 deductible. That's a difference of $150, or about 4%.
For someone choosing between those two trims, insurance alone probably shouldn't settle the decision. MoneyGeek's September 2026 trim data tells a different story because it uses a $1,000 deductible. Its figures range from $202 a month for a Standard Range to $380 for Launch Series Long Range, an 88% difference. While both figures are accurate for their own profile, they aren't measuring the same thing, so it's worth treating them separately rather than averaging them.
For used buyers, model year may be more useful than trim. Insure.com's annual figures are:
$3,468 for 2020
$3,343 for 2021
$3,722 for 2022
$3,708 for 2023
$3,605 for 2024
$3,836 for 2025
The jump from $3,605 in 2024 to $3,836 in 2025 lines up with the 2025 "Juniper" refresh — though the supplied data doesn't include a clean insurance-only split for the refresh itself, so treat the connection as directional rather than a precise number. If you're financing or leasing, consider Tesla gap insurance as part of the overall risk picture.
Tesla Insurance: Which States Can You Buy It In?
Tesla Insurance is available in a growing number of states, but it isn't a nationwide option. Tesla's own site lists 15 states — Arizona, California, Colorado, Florida, Illinois, Indiana, Maryland, Minnesota, Nevada, Ohio, Oregon, Tennessee, Texas, Utah, and Virginia.
Tesla's Own Insurance
Where You Can Buy Tesla Insurance Directly
Tesla Insurance is available in 15 states today. In most of them, Tesla can use driving behavior and your Safety Score to help set the monthly premium.
- Arizona
- California1 (see note 1)
- Colorado
- Florida
- Illinois
- Indiana
- Maryland
- Minnesota
- Nevada
- Ohio
- Oregon
- Tennessee
- Texas
- Utah
- Virginia
1. California is the exception.Tesla Insurance is sold there, but Real-Time Insurance is not — Tesla says the Safety Score is for educational purposes only in California and does not affect the premium.
Source: tesla.com/support/insurance/what-is-tesla-insurance, verified current as of Sept 15, 2026.
Tesla's model is different from a traditional insurer because, in most participating states, it can use driving behavior to help determine the monthly premium. Tesla says its Real-Time Insurance considers factors including how safely and how much you drive, your vehicle, location, coverage and Safety Score.
The business itself has been expanding. Tesla's total direct premiums rose 40.7% to about $1.37 billion in 2025, according to S&P Global, while its direct loss ratio improved to 100.4%, compared with roughly 60.4% for the U.S. property/casualty industry overall. Trade reporting also identified Q1 2026 as Tesla's first profitable underwriting quarter, helped in part by favorable reserve adjustments.
For a consumer, the loss-ratio number is worth knowing because it shows how different Tesla's insurance economics have been from the broader market. A carrier paying roughly as much in claims as it collects in premiums has less room to offer permanently aggressive pricing.
California remains the exception to Tesla's Safety Score model. Tesla Insurance is available there, but Real-Time insurance isn't; the Safety Score is educational and doesn't affect premiums.
Which Insurers Are Cheapest for a Model Y
Carrier matters as much as state. Based on currently available rate data, these five insurers post some of the lowest average monthly premiums for a Tesla Model Y:
Insurer Comparison
Which Insurers Are Cheapest for a Model Y
Average monthly and annual premiums by insurer for a Tesla Model Y, based on aggregated rate data.
| Insurer | Monthly | Annual |
|---|---|---|
| USAA | ~$187 | ~$2,244 |
| GEICO | ~$221 | ~$2,652 |
| State Farm | ~$223 | ~$2,676 |
| CSAA | ~$240 | ~$2,880 |
| Allstate | ~$248 | ~$2,976 |
Source: Aggregated rate data, not independently verified against a single original source. USAA is restricted to military members, veterans, and their families.
USAA is only available to military members, veterans, and their families, so for most shoppers GEICO and State Farm are the more realistic cheapest options. These figures come from aggregated SERP data rather than a single verified source.
Compare Tesla Model Y Insurance Quotes
The state table gives you a useful benchmark. However, your actual premium can still be higher or lower depending on your age, driving record, credit, coverage limits, deductible, insurer, and vehicle details.
That's why the most useful next step isn't to pick an insurer from a national average. It's to compare actual rates for your situation. Compare Tesla Model Y insurance rates with SaveMax Auto to see which quotes may offer the best fit for your coverage needs.
FAQs About Tesla Model Y Insurance
How Much Is Insurance on a Tesla Model Y?
About $3,836 a year, or $320 a month, for a 40-year-old driver with a clean record and good credit, 100/300/100 limits, and a $500 deductible, according to Insurance.com in April 2026. Published figures range from $2,538 to $4,752 because sources use different deductibles, model years, and methodologies. Your state matters more than any of that, however, as the same car runs $1,992 in Hawaii and $6,247 in Louisiana.
What Is the Cheapest State to Insure a Tesla?
Hawaii is the cheapest state at $1,992 per year for the Model Y in this dataset. Maine follows at $2,373, then Idaho at $2,395, Vermont at $2,536, and Indiana at $2,541. MoneyGeek's September 2026 analysis, using a different profile, also ranks Hawaii the cheapest and Louisiana the most expensive, making those endpoints unusually consistent across datasets.
Why Is Tesla Insurance So Expensive?
Repair costs are a major reason. Mitchell reports an average repairable claim severity of $6,042 for a battery-electric vehicle versus $4,902 for a gasoline vehicle in Q1 2026, and 84.74% of EV repair parts spending goes to OEM parts rather than aftermarket alternatives (Mitchell Q2 2026). Repair access is a factor, too. As of April 2025, there were only 51 Tesla Collision Centers nationwide, spread across 21 states — a count that has grown since. Total-loss risk adds to the picture as well: Kelley Blue Book reporting has found insurers are quicker to total a damaged Tesla than other cars, since even modest damage can cost more to fix than the car is worth.
Does the Model Y Performance Cost More to Insure?
A little, based on like-for-like figures. Insurance.com puts the Long Range at $3,786 a year, and the Performance at $3,936, a difference of about $150 or 4% for its April 2026 profile. MoneyGeek's profile figures show a much wider trim spread because they use a different $1,000 deductible. Your state, age, and deductible can have a much bigger effect than the trim itself.
Can I Buy Insurance Directly From Tesla?
Yes, if you live in one of the states where Tesla Insurance is currently offered. Tesla's own site lists 15 states: Arizona, California, Colorado, Florida, Illinois, Indiana, Maryland, Minnesota, Nevada, Ohio, Oregon, Tennessee, Texas, Utah, and Virginia. In most of these states, Tesla uses driving behavior and Safety Score information to determine premiums. California is the exception: Real-Time Insurance isn't available there, and Tesla says Safety Score is for educational purposes only and doesn't affect premiums.